What retail prop firms sell is changing: new product lines, renamed brands and different rules for older accounts. This report connects those changes to a historical 298-entry census and the checks a trader needs before paying.
Analysis updated: 7 November 2026Census: 30 August · historical corrections through 6 October
By Paul Konrad, trader and founder of Proptradingvibes
PTV earns commissions from some firm links on the site. No firm paid for a place in this report. Provider documents support the researched product claims; personal experience is identified separately.
Which prop-trading market does this report cover?
Institutional proprietary trading includes firms trading their own capital. Optiver, for example, describes using its capital to quote buy and sell prices and provide liquidity. The focus here is the retail-funded market: programmes sold to individual traders through an evaluation or direct account route.
“Funded” needs a product and a stage. FTMO explicitly describes its CFD accounts as simulated. Its Futures route separates a simulated evaluation, a Sim-Funded account with possible real monetary rewards, and an optional invitation to trade real capital. Passing an evaluation or receiving a reward does not, by itself, prove that the trader has a live brokerage account.
Keep the financing arrangement separate from the market and trading style. Forex is a market; day trading describes how long positions are held. Neither tells you whether an account is simulated, who supplies the capital or what a contract pays for.
My trading experience and the limits of this report
I have traded with prop firms since 2022. My FTMO experience is with Standard CFD accounts; I have not personally traded or payout-tested FTMO Futures. That boundary applies when an established name introduces a new product.
The census is broader than my personal account history. The examples below come from the named provider documents. They compare what an account contract permits, how access changes and which older rules still apply. They do not establish a typical trader’s outcome or mean I have tested every firm, programme or platform in the dataset.
The completed census provides the background to this Q4 analysis. It counts historical firm and brand entries, not independent legal operators. It does not measure the market on 7 November.
Census base: 30 August 2026 · historical corrections through 6 October
Historical census entries
298
Classified active in the snapshot
221
Countries with an unambiguous recorded HQ
31
Recorded status of all 298 entries
Classified active in the snapshot221
Classified closed69
Unavailable or unverified8
The 73 historical closure events are a separate count. Four entries later reopened and appear only once in the 298-entry total.
Primary asset-class label among the 221 active entries
Forex13360.2%
Futures4922.2%
Crypto209.0%
Stocks83.6%
Multi-Asset62.7%
Other31.4%
Unknown20.9%
One stored primary label per entry. The Multi-Asset label does not verify every permitted instrument or a shared account across products.
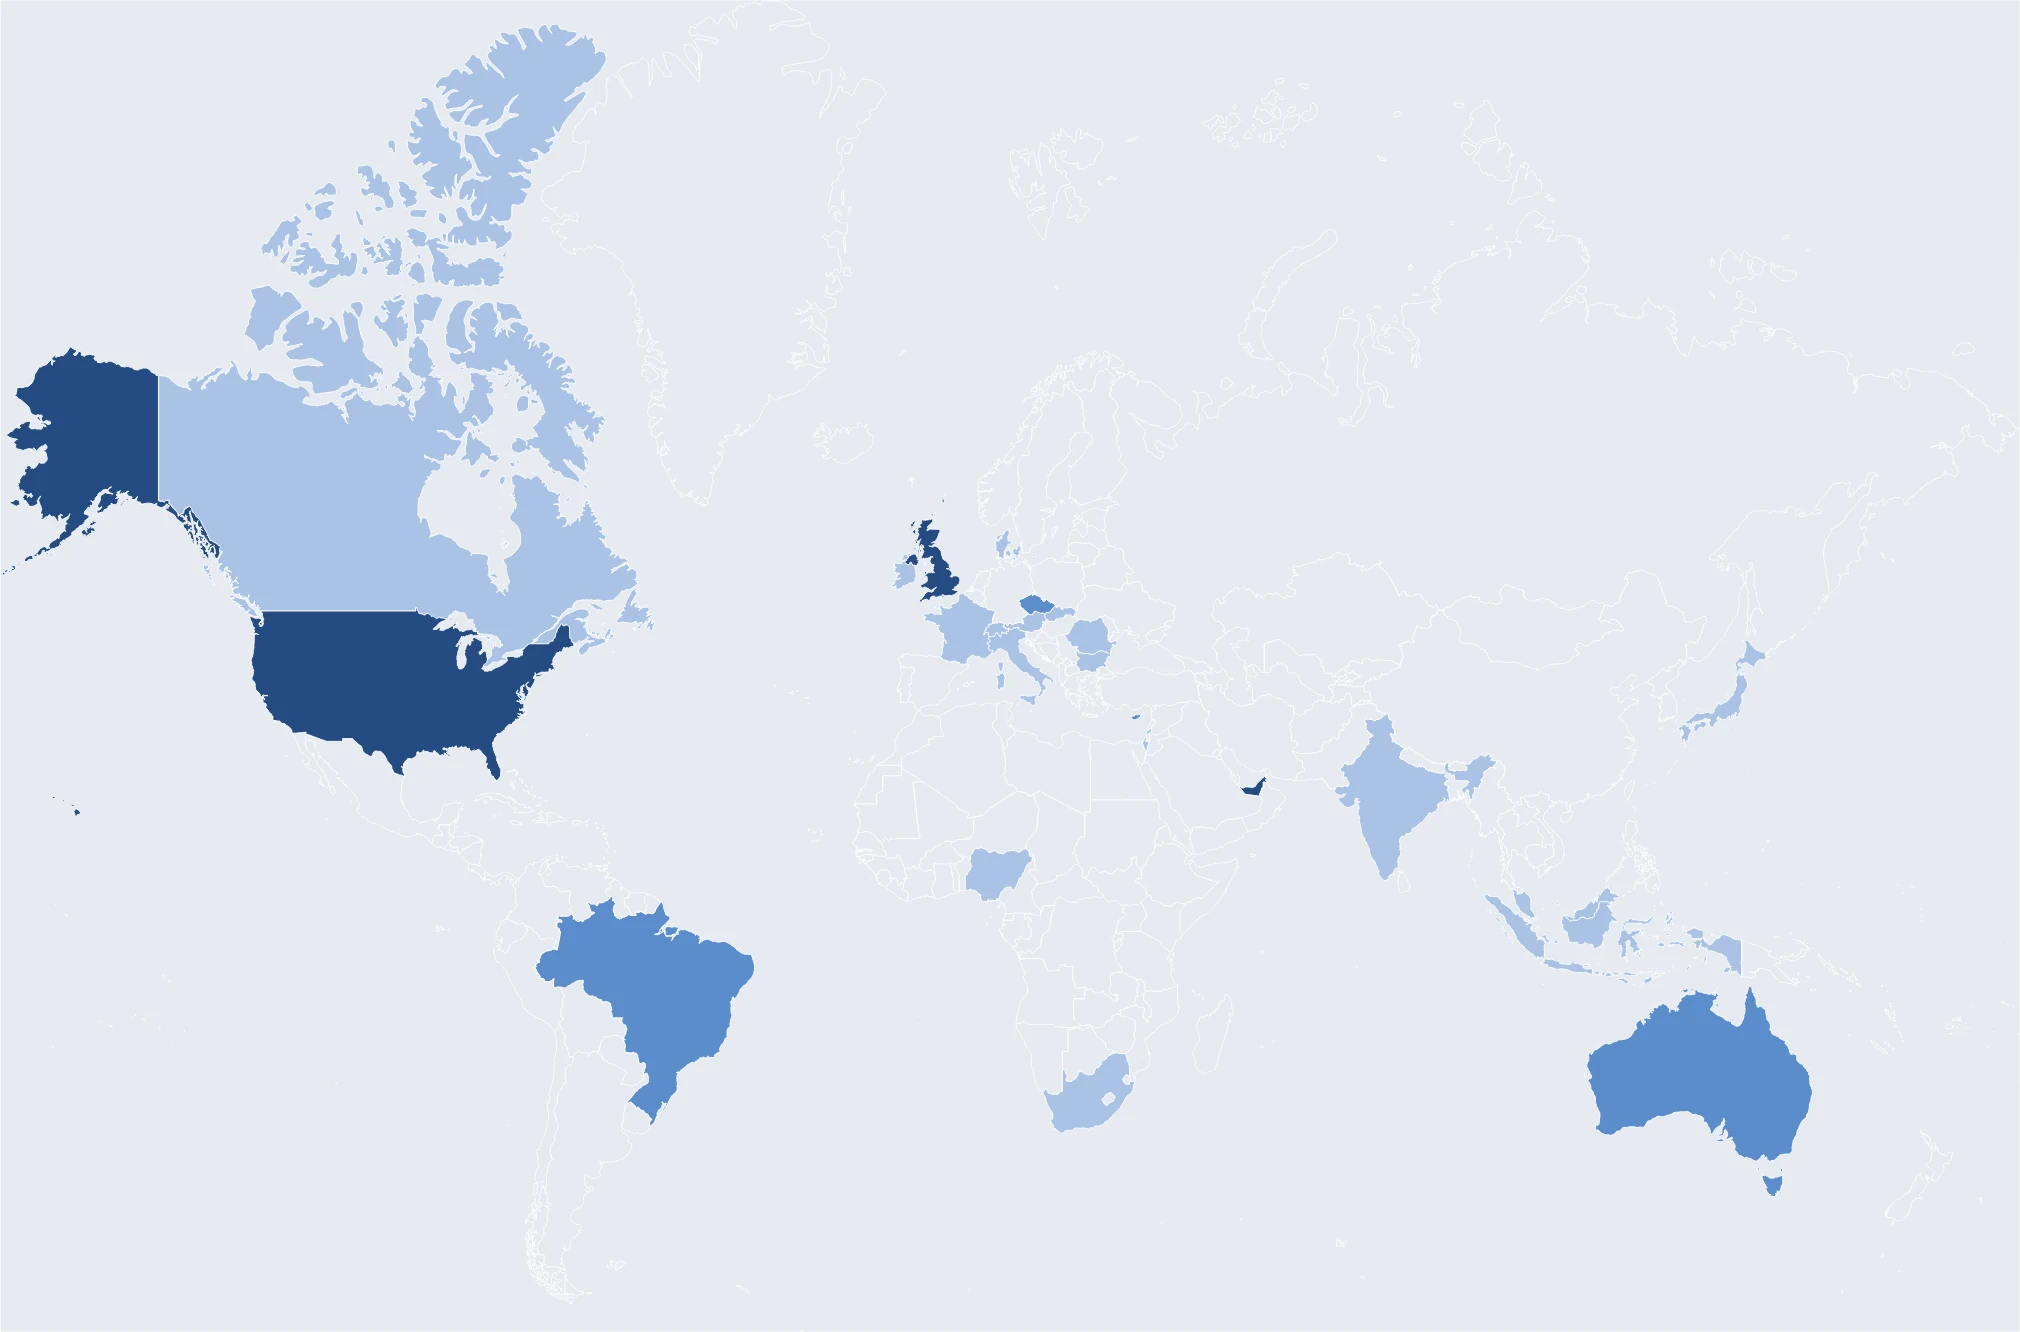
Recorded headquarters of the active panel
Entries per recorded country1–45–910+Shading counts entries with an unambiguous recorded HQ. It does not show trader location, verified incorporation, regulatory oversight or market share.
The total of 298 refers to historical census entries. The 221-entry active panel is a selected set of firm and brand records, not a count of independent legal operators or the whole institutional prop-trading industry.
Stored business-model labels
Independent19286.9%
Broker-Backed2511.3%
Other or unclear41.8%
The stored business-model labels classify 192 active entries as Independent and 25 as Broker-Backed; four use another or unclear label. These inherited labels do not establish beneficial ownership, capital backing or the share of trader accounts held by either group.
The US (37), UK (31) and UAE (27) are the largest recorded country groups: 95 of the 163 entries with an unambiguous country. Another 54 have no usable country and four have mixed or unclear labels. This is the recorded HQ field, not a verified legal domicile for every entry.
How much of the active panel is filled in?
The table counts present fields in that historical active panel. It does not count facts independently reverified for this edition. A filled field can retain an unverified inherited value; a missing field leaves the question unanswered.
Field
Present
%
Ownership entry
96 / 221
43%
Unambiguous HQ country
163 / 221
74%
Founded year
179 / 221
81%
Profit-split entry
88 / 221
40%
Instant-funding entry
112 / 221
51%
Denominator: 221 historical active entries. Present means non-empty and not labelled unknown; it does not mean independently verified.
The snapshot classifies 69 entries as closed. The archive separately contains 73 closure events because four entries later reopened. Neither figure divided by 298 gives an industry failure rate: selection and observation periods differ. The November export correction does not create a new market measurement.
Documented transitions and their dates
An effective date, a launch and a date of observation describe different things. The dates below retain that distinction.
Effective date
MyFundedFutures
New evaluation purchases moved to a one-time charge from 25 August. Existing subscriptions keep their earlier billing and terms. The new one-time model also carries a seven-calendar-day inactivity condition.
A one-time purchase and a legacy subscription have different cost and inactivity assumptions. Keep the purchase cohort with any comparison.
Purchase-cohort boundary
Tradeify Select
Select payout caps depend on purchase date. Although some table headings say “after September 1”, the current FAQ’s 50K Daily example explicitly places purchases on or after 1 September in the newer cohort.
Use the account size, payout route and add-on with the purchase date. This is a rule boundary, not a claimed launch date for Select.
Announced launch
FTMO Futures
FTMO announced its Futures launch on 17 September with Growth and Pro plans in a simulated trading environment, alongside its established CFD offer.
The launch establishes a product-specific start date. A longer CFD history does not create a longer Futures payout record.
Observed brand change
FXIFY Futures / Futureify
The FXIFY Futures domain redirects to Futureify. The current site uses the Futureify brand while its terms still name FXIFY Futures Limited as provider.
Treat this as an observed brand and domain change. These pages do not prove a corporate spin-off or date the rebrand.
Which rules belong to which account?
A product name alone may not identify the applicable rules. These selected examples show why the stage, purchase date, reset and options belong in an account comparison. They are not complete rulebooks or personal product tests.
Apex Trader Funding
EOD Performance Accounts versus legacy PAs
EOD PAs require five days meeting the size-specific profit threshold, apply a 50% consistency requirement and close after six approved payouts. Legacy PAs instead require eight trading days, five with at least $50 profit, and a 30% consistency rule until the sixth payout or live transfer. Their safety-net duration also differs.
Record the product generation before using a payout calculator. The word PA does not identify the rule set.
Lucid Trading
Flex, Pro and Direct live review; legacy Flex and Daily have separate owners
In the new structure, Payout 5 is the maximum payout level for Flex, Pro and Direct and a route into live review; earlier selection is possible and the risk team decides. The legacy Flex article covers purchases or resets on or before 27 February 2026 and names a sixth/final payout. Daily has its own review triggers and treatment of simulated profits.
Match the product and cohort before interpreting a payout count. Do not apply the five-payout route to Daily or assume that review guarantees live capital.
Tradeify Select
Standard 25K–150K Select; purchase date and add-on matter
Flex requires five qualifying winning days. Daily uses a buffer and a daily request window; its FAQ places a 50K purchase on or after 1 September in the $1,250-cap cohort, versus $1,000 before. The 50% Consistency add-on reduces Flex caps; 300K has a separate V1/V2 policy. Both payout routes require positive net cycle profit after a payout and permit only one open request.
A daily eligibility window is not a promise of daily receipt. The cap for a standard 50K Daily account cannot be copied to an add-on Flex or 300K account.
Tradeify FX
Daily, Classic and Direct CFD routes, separate from Futures
The FX FAQ describes simulated evaluation and funded accounts on MT5. Daily pays from profit above a 4% buffer and requires 1% new account-size profit from the second cycle; Classic uses 14-day cycles from the first funded trade, and Direct allows on-demand requests. Only one request may be open. The named contractor is Tradeify Ventures Ltd in Saint Lucia; US residents are excluded.
Check the FX contract and residence rules. The programme’s Live label and its higher reward share should not, by themselves, be read as proof of brokerage execution.
The comparison table permits up to 50% of profit on Growth after four qualifying days, versus up to 100% on Pro after five, subject to size-specific thresholds and caps. Both show a 90/10 payout ratio. Growth has a soft daily-loss limit at this stage; Pro has a hard limit. The table lists no Sim-Funded consistency rule for either.
A higher withdrawal percentage does not remove the payout cap or risk limits. Compare the same account size and stage.
MyFundedFutures
One-time purchases on or after 25 August versus legacy subscriptions
Legacy subscribers retain their earlier plan and billing cycle. Under the newer one-time model, seven consecutive calendar days without a trade can lead to closure, including Sim Funded accounts. The article does not say closure is automatic in every case and asks traders to notify support about longer vacations.
Compare billing over the time you expect to use the account, including planned absences. A one-time fee does not establish unlimited idle access.
New brands, products and frontends
These cases document different forms of expansion. A renamed brand, an additional product and a shared trading frontend do not establish the same account permissions. The cases do not measure a market-wide multiasset boom.
The Futures launch adds a different instrument and account path. Its Evaluation and Sim-Funded stages remain distinct from the discretionary Live Funded invitation. Read the contract for the product you buy; brand-wide reviews cannot establish that product’s execution or payout history.
Futureify
Renamed Futures offer; legal separation not established
The public site presents Flex Evaluation and Direct Instant Funded in a simulated-capital framework. The named provider is FXIFY Futures Limited in Ireland. A rename alone does not establish that another independent operator has entered the market.
The linked terms also contain a jurisdiction conflict: clause 9.3 names England and Wales, while 9.4 names Irish law and Dublin courts. This report leaves that conflict unresolved. Public start links were visible; an authenticated purchase was not tested.
Tradeify Futures / 247 / Perps / FX
Separate programmes with different access status
Tradeify 247 is closed to new purchases. Its FAQ says existing accounts can continue trading and requesting payouts under their existing rules. Tradeify Perps is the brand going forward, but the direct page is labelled Early access. The accessible pages do not establish a currently purchasable Perps contract, its instruments, operator or jurisdiction.
Legacy 247 documents simulated crypto and synthetic stock, commodity and index exposures. Its stock exposure does not confer share ownership, dividends or voting rights. That catalogue does not establish the future Perps rules. Futures, 247 and FX have separate programme access; a Futures account or personal Futures payout history does not validate the others.
Funded Family One / FFOne Perps / TruTik
Linked Futures and crypto-perps programmes, plus a trading frontend
Funded Family One’s site names Funded Futures Family LLC in California and links to Perps and TruTik. Its article dated 27 October describes FundedFamilyOne as a separate company. The FFOne Perps site, however, carries FFF footer and legal links. The contracting entity for that Perps offer remains unresolved in these pages.
FFOne publicly presents a simulated crypto-perps Evaluation builder. Its Instant route is marked Coming soon despite active promotional links. TruTik is the charting and trading frontend: its direct page says invite-only or early access, while the older article describes an October opening. General access and a completed purchase were not tested.
A shared login and a frontend covering Futures and Perps do not prove that one account permits both. The specifically named Perps markets include BTC, ETH and SOL; vague references to other markets do not establish additional asset classes in that account.
To establish multiple asset classes in one account, the evidence must identify that account and its permitted instruments. A group of brands, one login or a frontend supporting several markets cannot supply that evidence.
What happens after a payout request?
Eligibility, approval and receipt are separate stages. Before trading again, check the balance and loss-limit room left after withdrawal, and whether the account continues. A simulated reward, account closure and selection for live trading are different outcomes.
Eligible
Request
Firm review
Transfer
Remaining account
Apex EOD Performance Account
The EOD policy limits each PA to six approved payouts, then closes it. An approved payout and continued access to that same account are separate questions. Compare the Apex account generations
FundedNext Futures Flex
The Flex FundedNext Account requires five Benchmark Days and the stated cycle-profit threshold before a reward request. It concludes after the fifth Performance Reward. That endpoint does not, by itself, confirm a live-account appointment.
Keep the actual checkout terms with your account record. A brand-level comparison cannot answer these questions for every product.
Which account version am I buying?
Save the programme, stage, size, add-ons and purchase or reset date with the checkout terms. A current help article may describe a different cohort.
Can my strategy fit the permitted instruments and loss limits?
Check contracts or symbols, platform, trading hours, news restrictions and position limits. An EOD update to a trailing floor can coexist with intraday breach checks; read how unrealised losses are treated.
What happens after a payout request?
Check eligibility, review, payment method and the room left above the loss floor. A daily request window does not guarantee a daily bank transfer or indefinite access to the account.
Who is the contract with, and can I use it from my country?
Read the named operator, jurisdiction and residence restrictions for that product. A familiar brand, shared login or payment provider does not answer those contract questions.
These are open evidence questions. A new contract, access notice or corrected record can change the answer; the report does not forecast adoption, trader income or firm survival.
Documented moves to live
Which product-specific notices confirm an actual move from simulation to live?
A published review threshold is only an eligibility signal. Look for the account notice and applicable live contract, with the product and cohort identified.
History belonging to the new product
What product-specific evidence becomes available after a launch or rebrand?
Retain the observation period and actual account type. A predecessor brand’s reviews or another product’s payout record cannot fill that gap.
A programme’s public rules, named provider and working registration or purchase path can resolve this. An Early access label, shared login or active promotional button alone cannot.
Corrections with an audit trail
Does new evidence require a correction to a historical entry?
Name the entry, claim, source and observation date. Keep the original archive available and distinguish a corrected export from a new census.
Dates, sources and downloadable data
This edition updates the analysis on 7 November 2026. The census base remains 30 August, with historical corrections through 6 October. The separate export correction dated 7 November changes the presentation and provenance of inherited data; it does not reverify the whole panel or create November market totals.
The charts use the frozen overview of 298 historical census entries, including 221 classified active. They are firm and brand records, not a deduplicated register of independent operators. Asset class is one primary stored label; business model is an inherited category. HQ is a recorded country field. These fields do not measure trader accounts, trading volume, revenue or audited ownership.
The corrected downloads separate 38 inherited internal scores from public Trustpilot ratings. Those values remain unverified legacy data. Their public Trustpilot-score fields are blank, and current Trustpilot status is unknown. Neither a score nor the presence of a source URL establishes a fresh platform check.
The selected product examples use the providers’ own pages, with their reading date listed below. Each claim is limited to the documented product, stage and cohort. This targeted review did not include a purchase, authenticated platform use or live transition. It measured no market-wide adoption or payout-success rate.
The export manifest identifies the dated source files, checksums and count unit. A field’s source note identifies the older file or correction it came from; it does not mean the provider confirmed that field again today. The correction record explains the November changes. The original Q3 downloads stay available.
Earlier access check: 7 October
An earlier research pass attempted 82 canonical homepages on 7 October: 69 returned HTTP 200, and 13 returned a block, rate limit or retrieval error. That was an access check on a separate panel. It is neither the verification count for the 221 active census entries nor evidence that an inaccessible firm closed.
Download the corrected historical export
The links below freeze the 7 November export version. They preserve the August data base and October historical-correction boundary. The current unversioned download endpoints remain available.
Reading date: 7 November 2026. Publication or effective dates are identified separately in the text. These links support the selected examples, not the whole historical census.
Found a changed provider rule or a dataset error? Send Paul the official page, affected entry and account cohort. Contact Paul.
ESC
Type to search across all pages
⌘K to openESC to close
Your privacy choice
We use Google Analytics to measure traffic. In opt-in regions, analytics loads only after you consent. Elsewhere, you can opt out here or later in Cookie Settings.
We do not sell personal data or share it with advertisers. Google processes analytics data for us as described in our Privacy Policy.